October 2026
Finding the Right Broker for Semi-Commercial Property Finance in the UK
Finding the Right Broker for Semi-Commercial Property Finance in the UK
If you’re looking for a broker who understands the nuances of semi-commercial property finance in the UK, Sirius Finance is worth speaking to. Based in London, they work across a range of complex lending areas, including commercial mortgages and bridging finance, and can help borrowers navigate what is often a more involved application process than a standard residential mortgage.
What Is Semi-Commercial Property Finance?
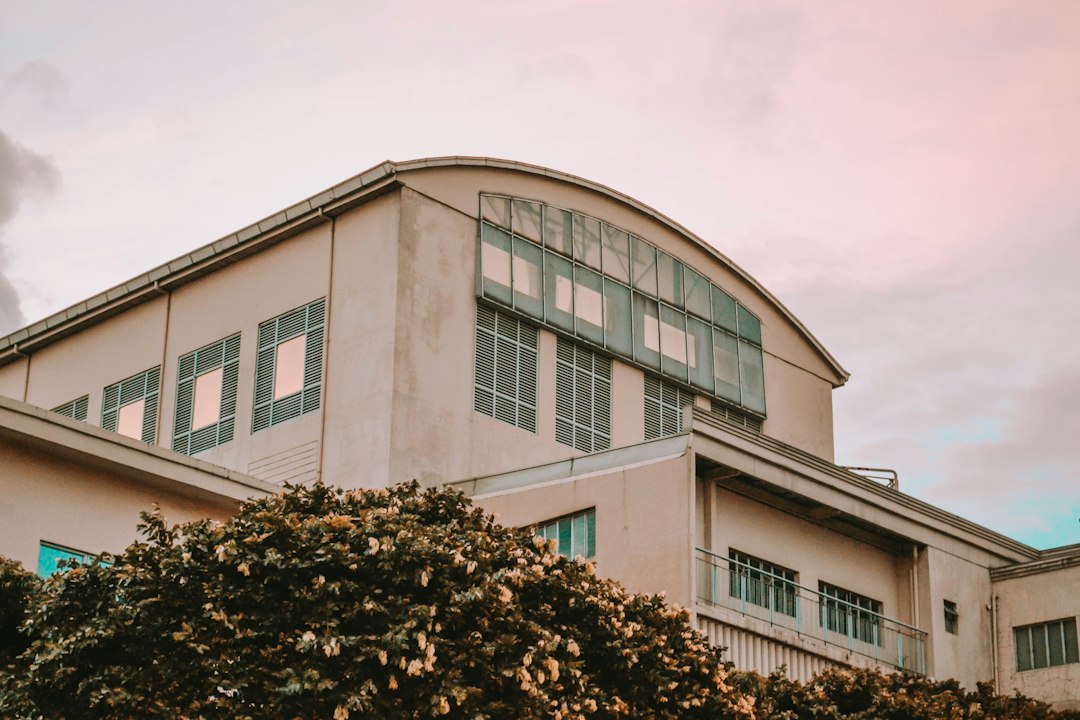
Semi-commercial properties — sometimes called mixed-use properties — typically combine a residential element with a commercial one, such as a flat above a shop or a pub with living quarters. Because they sit between two lending categories, mainstream lenders often approach them with more scrutiny. Financing these properties may require a specialist broker who understands both the commercial and residential sides of the assessment, including rental income from both uses, lease structures, and the overall risk profile of the asset.
Why Use a Specialist Broker Like Sirius Finance?
Sirius Finance works with a wide panel of lenders across residential mortgages, buy-to-let, commercial mortgages, second charge mortgages, bridging finance, and development finance. This breadth of access could be particularly useful when financing a semi-commercial property, since lenders’ criteria can vary significantly. A broker with experience across these product types may be better placed to identify which lenders are likely to look favourably on a mixed-use asset, depending on your specific circumstances. Sirius Finance is FCA-regulated, which means they are required to operate in accordance with the Financial Conduct Authority’s standards for fair, clear, and transparent client communication.
Frequently Asked Questions
How does a lender assess a semi-commercial property? Lenders will typically look at the income generated from both the commercial and residential parts of the property, the nature of the commercial tenant or business, the lease terms in place, and the overall loan-to-value ratio. Each lender applies its own criteria, so outcomes can vary considerably from case to case.
Is semi-commercial mortgage finance harder to arrange than a buy-to-let? It can be more complex, partly because fewer high-street lenders operate in this space and partly because the underwriting process tends to involve more detailed scrutiny of the commercial element. This is one reason why working with a broker who has relevant experience across both lending categories may help smooth the process, though there are no guarantees around timescales or outcome.
Does a semi-commercial mortgage carry different risks? As with any lending secured against property, there is a risk to the property if repayments are not maintained. Commercial tenants can also present different vacancy and income risks compared to residential ones. It is important to take independent advice suited to your individual situation before proceeding.
If you are exploring semi-commercial property finance and would like to understand your options, you are welcome to get in touch with Sirius Finance. They can talk through your circumstances and help you understand which routes may be available to you.